DC Insights

Vietnam’s economy remained strong in 7M26, driven by robust manufacturing expansion and record FDI inflows, while easing inflation created additional policy flexibility.
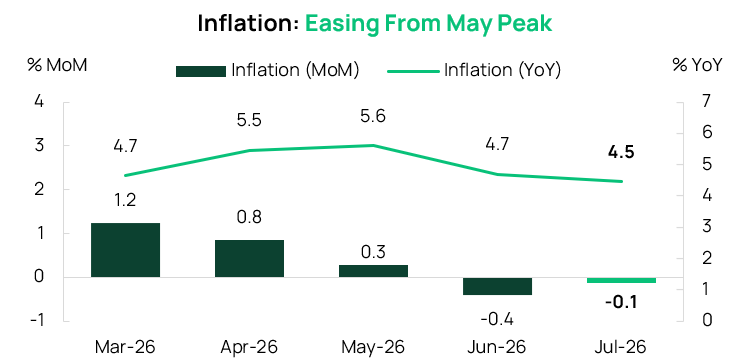
July offered a test the market rarely sets this cleanly: some of the strongest production data in years against the index’s sharpest monthly fall since March. The domestic question, whether the first half’s growth composition could hold its momentum, was answered clearly. Capacity formation accelerated through every channel, and inflation fell MoM for a second consecutive month, confirming May as the peak.
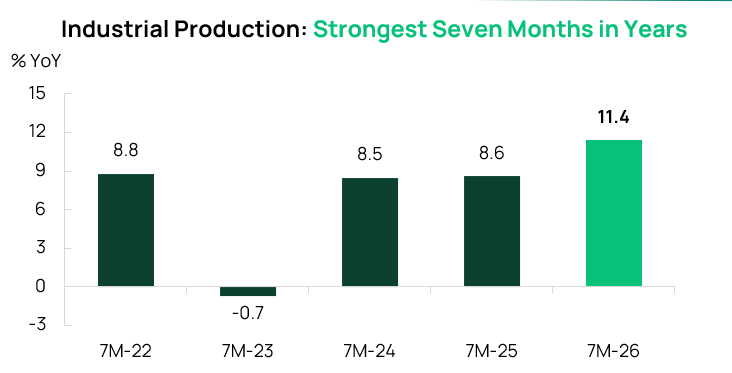
Manufacturing gave the clearest reading. IIP rose 14.5% YoY in July and 11.4% in 7M26, the strongest seven-month run in years, with breadth holding across metals, motor vehicles and electronics. PMI climbed to a five-month high of 52.9, corroborating the official series. The more telling number is manufacturing employment, up 3.3% YoY: firms are adding people and plant, not just running existing capacity harder. Capital deployment tells the same story from two directions.
Public investment disbursement rose 25.9% YoY in July, taking 7M26 to 39.0% of the annual plan, with the usual year-end acceleration still ahead. Realised FDI of $15.2bn was the strongest seven-month total in five years, up 11.8% and 82.6% directed to manufacturing, while registered FDI rose 58.0% to $38.1bn. Domestic and foreign capital are being committed to the production base simultaneously, and at scale.
Imports are where that build shows up first. Import growth of 34.8% YoY in 7M26 ran well ahead of exports at 21.7%, swinging the trade balance from a $10.4bn surplus a year earlier to a $20.5bn deficit. The composition defuses most of the alarm: 94.1% of imports were production inputs, led by electronics and computer components, up 65.9% to $135.8bn. This is the investment cycle in transit rather than consumption outrunning income, though the import build will need to convert into exports for the external accounts to rebalance. Retail sales, up 13.1% in 7M26 and 7.5% in real terms, remain steady support rather than the swing factor.
Inflation was the month’s most important quiet release. CPI fell 0.1% MoM, a second consecutive decline that has taken more than a point off May’s 5.6% YoY peak, and the 7M26 average of 4.4% sits below the government’s 4.5–5.0% ceiling. Core inflation at 4.6% and utility costs still warrant monitoring, but the direction has turned: policy room that looked compressed in May is reopening just as the investment cycle asks more of it.
The index spent July trading the world rather than Vietnam. The VN-Index fell 6.3% in USD terms to close at 1,735.8, with the damage concentrated in the week to 24 July, a 5.7% drop on Middle East risk, oil and US trade-policy headlines. The recovery was quick, with the index reclaiming 1,700 by 29 July, though foreign investors net sold roughly $430mn on HOSE and breadth stayed uneven. The second half therefore starts constructive but more selective. FTSE implementation in September, lighter foreign positioning after months of net selling and reopening policy room all point towards a more positive outlook for the index in the coming months.
Read more about our previous monthly report Vietnam Market Insights – June 2026 here.