Fund
Fund Performance
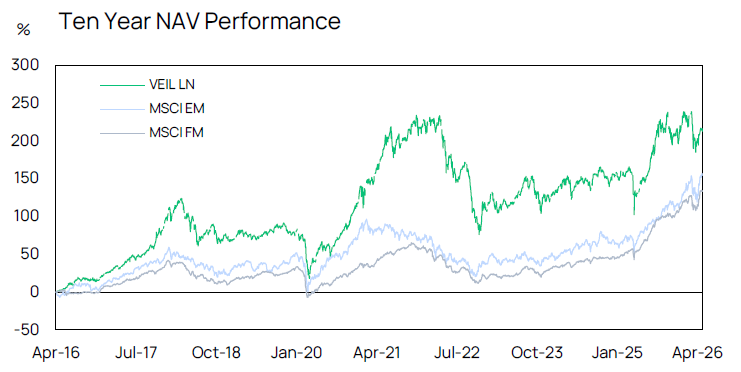
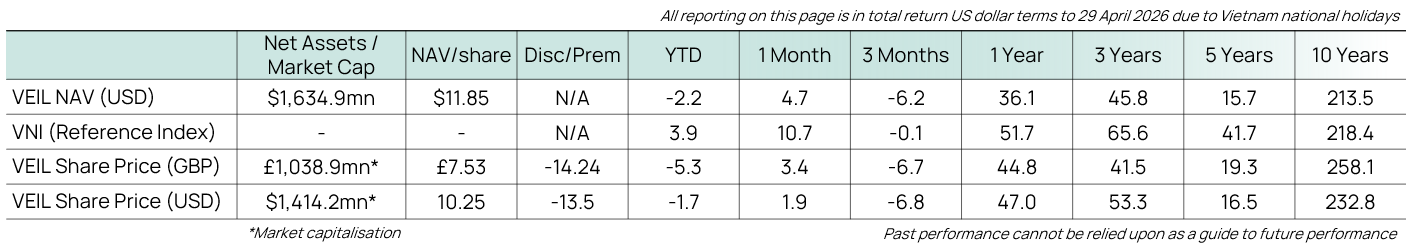
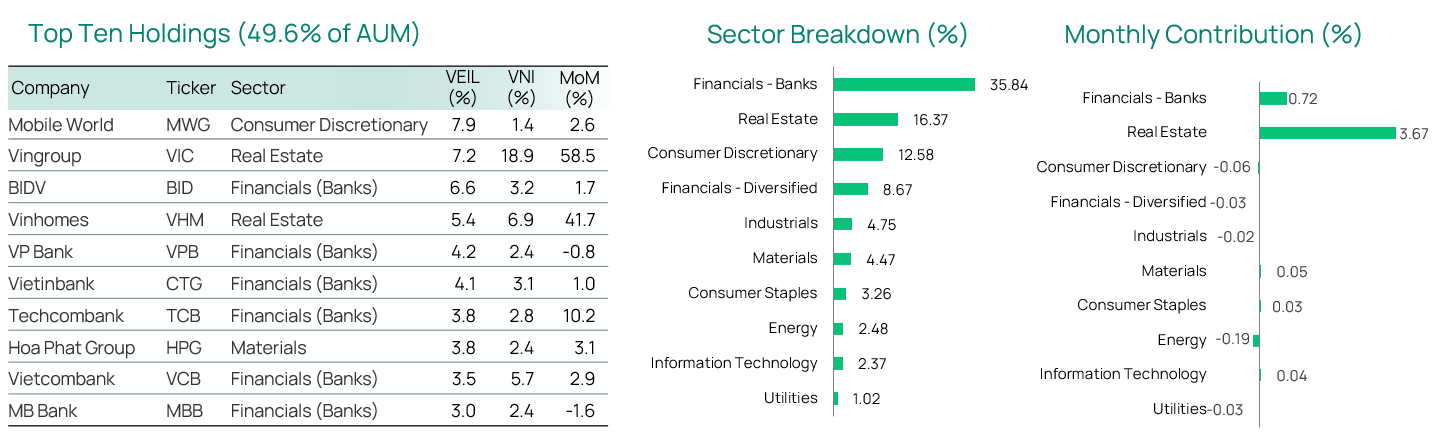
VEIL’s NAV rose 4.7% in April, lagging the VNI’s 10.7% gain. The rally was concentrated in VIC and VHM after they raised 2026 guidance at their 23 April AGMs. We trimmed both in Q1 to take profit on their 2025 runs and to reduce property exposure as interest rates increased in early 2026. These two names accounted for 25.8% of the VNI at end of April, but only 12.6% of VEIL, making the Fund’s structural underweight the primary driver of the month’s active return shortfall.
Positioning skewed defensive in April given the volatile US-Iran conflict. We cut high-beta exposure across brokerages (SSI, TCX, VPX) and select banks, rotating into ACB and MBB on attractive valuations and solid fundamentals. BID was trimmed after its private placement lifted the portfolio position size. Banks added 0.7% to performance overall, led by TCB (+10.2%) and STB (+8.5%), while steelmaker HPG (+3.1%) gained on improving demand and prices. In retail, the sector delivered the cleanest Q1 earnings beat, alongside April retail sales growth of 12.1% YoY. This supports our positive view on consumption, although price performance was mixed on the month with MWG (+2.6%) holding steady and PNJ (-6.6%) and FRT (-5.1%) softening. Detractors PVD (-10.9%), PVS (-5.9%), DCM (-11.6%) and DPM (-11.2%) gave back gains post-ceasefire announcement; we took profit on DCM but retained the others, with urea prices still above pre-disruption levels and PVD/PVS continuing to serve as a modest oil hedge.
Beyond FTSE’s upgrade to Secondary EM status in September, progress on non-prefunding and the Central Counterparty system narrows the gap to MSCI’s watchlist. The portfolio trades at 10.5x FY26 P/E against 27.6% EPS growth, and we have started deploying elevated cash into recent weakness. With earnings broader than the narrow rally suggests, we expect the portfolio to gain ground as prices catch up to fundamentals.
Hoa Phat Group (HPG) is Vietnam’s largest integrated steelmaker with total assets exceeding $10bn, commanding over 30% of the domestic hot rolled coil (HRC) market and approximately 40% of construction steel. Its fully integrated blast-furnace model at the Dung Quat plant, energy self-sufficiency, and proprietary port logistics underpin a structurally lower cost base than domestic and regional peers.
The 1Q26 results made the bull case concrete. Public infrastructure spending (expressways, the North-South high-speed rail, and metro lines) is driving rebar consumption, while a recovering property market layers on incremental demand. Both engines firing simultaneously drove rebar volumes up 30% YoY and HRC up 46% YoY, with total finished steel reaching 3.3 million mt (+39% YoY). For 2026, we expect total volumes of 14 million mt (+36% YoY), supported by long steel ASPs tracking +8% YoY and HRC at $562/mt (+12% YoY) on extended anti-dumping duties on Chinese imports, a structural rather than cyclical support. With Dung Quat 2 plant’s absorption costs rolling off, steel EBITDA margins are moving from the mid-teens into the low twenties on record volumes, firming prices, and falling unit costs, converging for the first time in three years. As HPG transitions from its capex-heavy phase into free cash flow generation in 2H26, we expect a re-rating to follow the earnings.
Read more about our previous VEIL Monthly Report – March 2025 here.