

Fund
Fund Performance

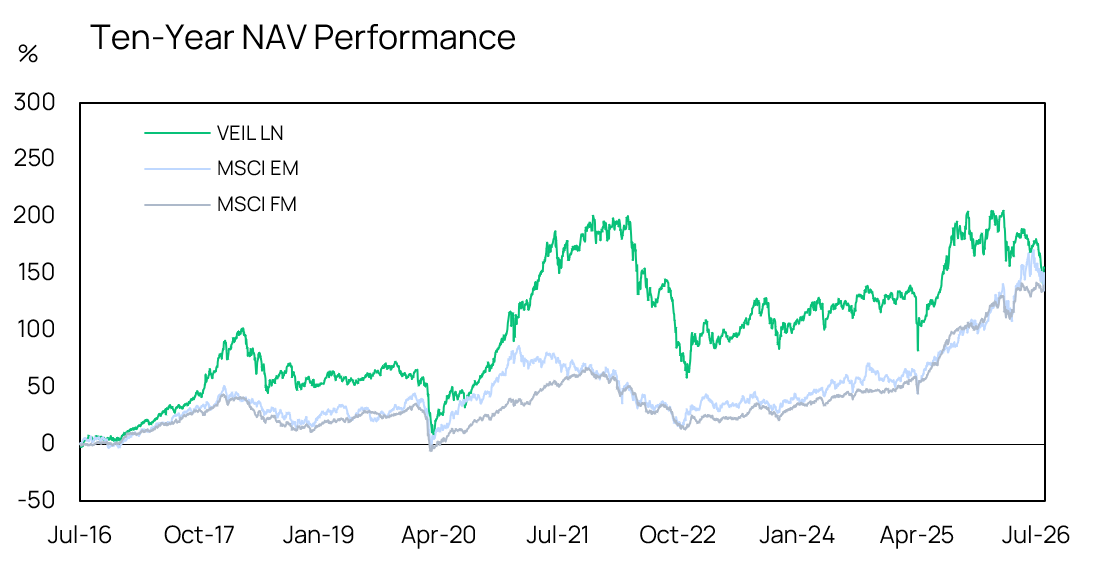
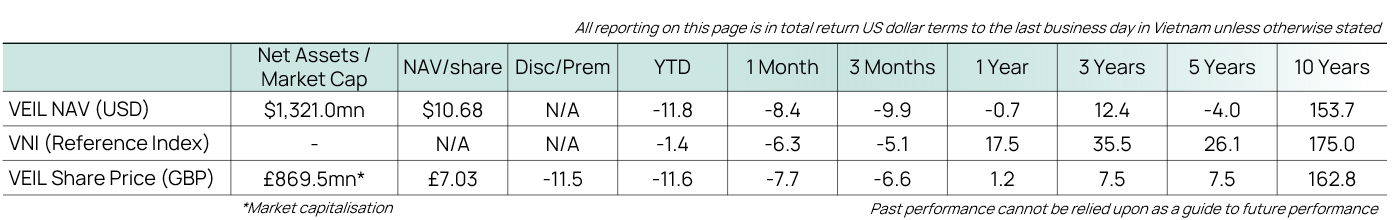
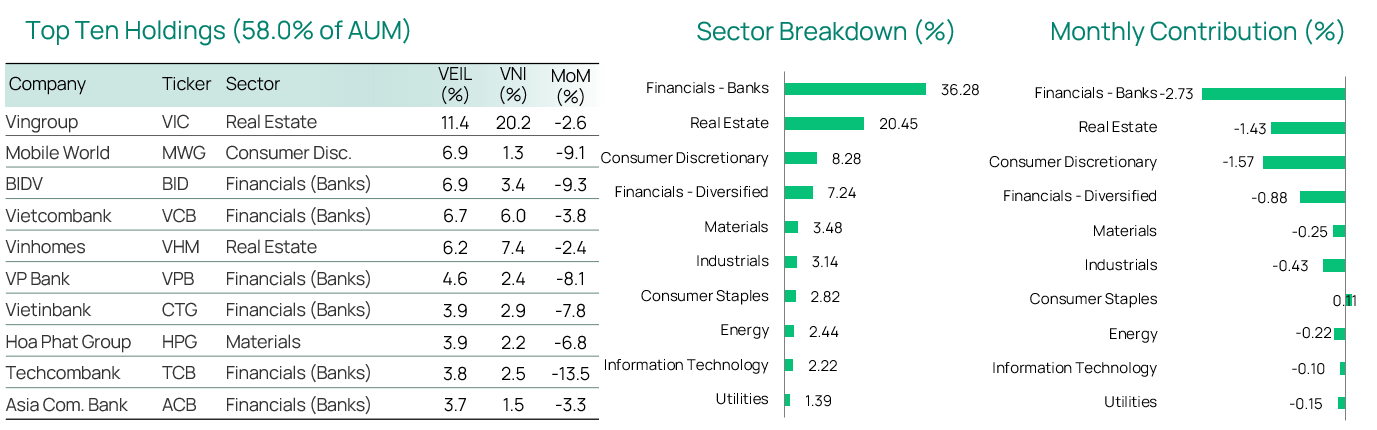
VEIL’s NAV fell 8.4% in July against the VN-Index’s 6.3% decline, taking the year-to-date return to -11.8% versus the index’s -1.4%. Roughly half the gap came from PNJ (-50.8%), which cost 1.0 percentage point of return. An ongoing investigation into alleged diamond smuggling involving a former executive of P-Lab, PNJ’s gemstone-certification subsidiary, triggered heavy selling across the jewellery industry; on our current understanding, the investigation concerns alleged conduct involving the individual rather than allegations of corporate wrongdoing by PNJ. PNJ has stated that its diamonds are legally imported. The shares have stabilised since the bottom in end of July.
The wider decline reflected the new US tariffs taking effect and tight system liquidity. Our retail and mid-cap residential overweights bore the brunt; VNM (+11.2%) and GMD (+4.7%) were among the few contributors. Cash averaged above 9% ahead of the Tender Offer settlement, with net cash at 2.1% by month-end. Property exposure fell 1.3 points, partly our reduction of mid-cap developers on refinancing risk, and we added to brokers ahead of September’s FTSE upgrade.
Fundamentals point the other way: 2Q26 earnings for Dragon Capital’s top 100 companies rose 31.9% YoY, CPI eased to 4.45% and exports grew 21.7% in 7M26. The ex-Vingroup market trades near 10x trailing earnings; the portfolio stands at 9.7x FY26 P/E on 24.7% EPS growth. Liquidity is the swing factor: until public investment, at 39% of plan through July, recycles Treasury cash into deposits, the market stays vulnerable, and we believe current valuations already discount much of that risk.
Gemadept (GMD) is Vietnam’s largest private port operator, with a market capitalisation of approximately $1.3bn anchored by the Gemalink deep-water terminal at Cai Mep and the Nam Dinh Vu complex in Hai Phong. Deep-water berth capacity at strategic locations is the scarce asset in Vietnam’s export infrastructure, and GMD’s pricing reflects it: Gemalink raised handling tariffs by 10% in February and still grew volumes 26% YoY in 2Q26, while the Nam Dinh Vu Phase 3 and Gemalink Phase 2 expansions roughly double group capacity by 2028. 2Q core net profit rose 53% YoY on revenue growth of 18%, with gross margin widening to 49.4% from 43.1% a year earlier as charges for port services rose, and logistics sales and gross margin expanded on improving shipping freight rates. Reported profit was further lifted by a one-off gain of approximately $23mn on the divestment of its logistics joint venture. First-half core profit already covers 57% of full-year forecasts, suggesting upside to estimates. The shares rose 4.7% in July, one of the few positive contributors in the portfolio. GMD trades at 15.5x forward earnings against forecast EPS growth of 31%. Tariff-related front-loading of exports may borrow from second-half volumes; our thesis rests on scarce capacity and pricing power rather than trade-cycle timing.
Read more about our previous VEIL Monthly Report – June 2025 here.

